
Ava Finance
- Rating
- 4.7
- Downloads
- 500.00K
- Content Rating
- Everyone
Ava Finance - Screenshots
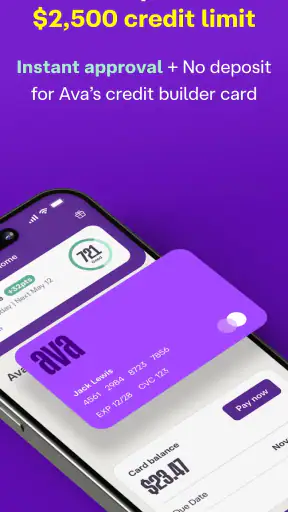
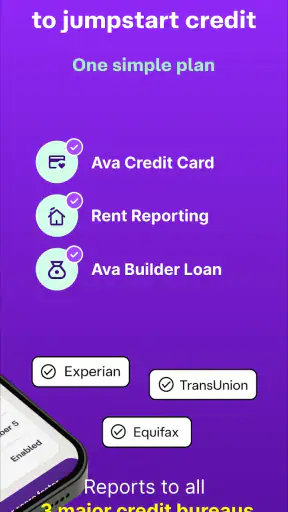
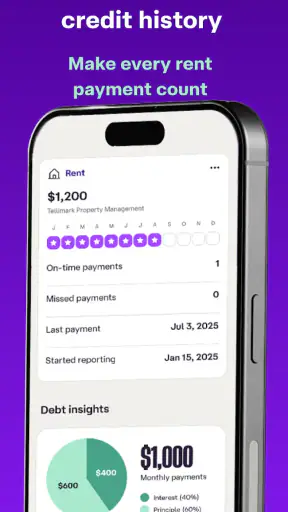
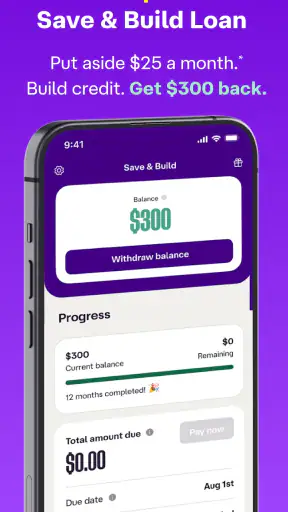
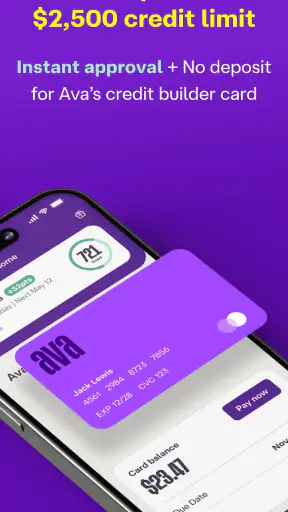
Pros
- Clear overview of balances
- debts
- and repayment progress
- Supports multiple account types in one financial dashboard
- Useful reminders can help prevent missed payment dates
- Simple interface makes routine tracking quick to understand
- Helpful insights can reveal spending and debt-management patterns
Cons
- Some features may require linking sensitive financial accounts
- Account synchronization can occasionally be delayed or inaccurate
- Advanced tools may be limited without a paid subscription
- Not all banks or financial institutions may be supported
- Financial recommendations should be checked before making major decisions
Ava Finance - Description
- App Name
- Ava Finance
- Package Name
- com.meetava.avaapp
- Developer
- Ava Finance, Inc.
- Category
- Finance
- Last Updated
- May 10, 2021
- Version
- 5.1.6626
Building credit can feel frustrating when the usual advice is vague, slow, or difficult to fit around everyday spending. I approached Ava Finance as a practical finance app rather than a general budgeting tool, focusing on its central promise: helping users build credit through a more structured borrowing experience. My impression is that it is most useful for someone who wants a guided way to think about credit activity, not for someone looking for a complete replacement for a bank, a detailed expense tracker, or professional financial advice.
The app comes from Ava Finance, Inc. and is available free of charge for users aged Everyone. It has attracted over 500 thousand installs, with a 4.7 average from around 17 thousand ratings and roughly 1.7 thousand written reviews. Those figures suggest that the app has found a clear audience, but they do not remove the need to understand how it fits into your own finances. Credit-building products are only helpful when the repayment routine is manageable, and that is the point I kept returning to while using it.
How Ava’s credit-building focus works in everyday use
The defining capability here is not simply “getting access to money.” It is the attempt to make credit-building feel more approachable by putting that goal at the center of the experience. Instead of opening the app with a broad collection of unrelated financial tools, I found the experience easier to understand when viewed as a guided credit routine: check what is available to me, understand the repayment responsibility, and keep the activity aligned with a realistic budget.
That distinction matters. A conventional credit card often encourages users to think first about purchases and only later about the statement balance. A traditional loan usually begins with a fixed amount, a fixed schedule, and a clear repayment obligation. Ava sits in a different space. Its value depends less on making a large purchase and more on helping a user establish consistent, controlled credit behavior.
I would not treat the app as a shortcut to excellent credit. No finance app can turn missed payments into positive history, and no credit-building product makes responsible repayment optional. The useful part is the structure. When an app keeps the credit goal visible, it can be easier to connect each decision with the longer-term result rather than treating borrowing as free spending.
For a first-time borrower, that focus can be less intimidating than opening a standard credit card and trying to interpret unfamiliar terms alone. For someone who already understands utilization, due dates, and repayment planning, the experience may feel more limited because the app is designed around a narrower objective. I see that narrowness as both its strongest feature and its main limitation.
The capability is most valuable when it creates a repeatable habit
The practical benefit is not one dramatic action inside the app. It is the possibility of turning credit-building into a repeatable habit. I found it helpful to think of the app as a checkpoint before taking on credit activity: What am I using this for? Can I repay it comfortably? Will this fit alongside rent, utilities, food, and existing obligations?
That mental pause is easy to overlook with ordinary credit products. A card can be convenient precisely because it removes friction, but less friction can also make overspending easier. Ava’s credit-centered design is more useful when it encourages deliberate decisions. The user should still keep a separate personal budget, because a credit app cannot know every upcoming bill or irregular expense that may affect repayment.
One non-obvious advantage is that the app can serve as a learning layer between having no credit routine and managing several conventional accounts. I would use it to practice checking obligations regularly, setting aside repayment money, and distinguishing available credit from money I truly own. That last distinction is especially important for younger users or anyone rebuilding after financial difficulty.
What the first setup feels like
When approaching Ava, I would expect to spend time reviewing the terms presented during setup rather than tapping through quickly. Finance apps can ask for information that affects eligibility, account access, or the way a product works. The responsible approach is to read each screen, confirm that the repayment arrangement makes sense, and avoid proceeding simply because the app makes the next step easy to reach.
I also recommend deciding on a personal limit before using any credit-building facility. For example, I might choose to use it only for a small recurring need that I already know how to cover, rather than treating the available amount as extra income. This is a stronger workflow than waiting until the end of a cycle to discover whether the balance is affordable.
Another useful habit is to keep records outside the app. I would note the amount used, the expected repayment date, and the bank balance reserved for it. That may sound overly cautious, but it protects against a common mistake: assuming that an app’s balance is the same thing as a complete picture of household cash flow.
A realistic scenario: starting a credit routine without chasing rewards
Imagine someone who has recently begun earning a regular income but has little or no established credit history. They want to build a record, yet they are nervous about a conventional credit card because they have seen friends carry balances from month to month. In that situation, I would suggest using Ava only for a predictable expense that is already included in the monthly budget, then checking the obligation regularly and reserving the repayment money immediately.
The important detail is that the user is not borrowing to solve a cash shortage. They are using a controlled amount as part of a planned routine. If an unexpected medical bill, reduced work schedule, or urgent household repair appears, I would pause the credit-building activity rather than stretch the budget. Credit-building should come after essential financial stability, not before it.
This scenario also shows why the app may be easier to recommend to a beginner than to an experienced card user. The beginner may benefit from a focused process and a clear reason for using the product. The experienced user may prefer a conventional card with broader payment flexibility, rewards, merchant acceptance, and a longer history of account management.
Where it differs from common alternatives
A standard credit card is usually the more flexible alternative. It can be used across many merchants, may offer rewards, and can become part of a broader financial setup. However, that flexibility brings more decisions: credit limits, statement balances, minimum payments, interest, and the temptation to spend beyond a planned amount. Ava’s focused credit-building approach may be easier to manage for someone whose priority is establishing disciplined behavior rather than maximizing card features.
A secured card is another familiar alternative. It may suit a user who can provide a deposit and wants a conventional card structure. The trade-off is that the user must be comfortable tying up money as security and managing a card account directly. Ava can appeal to someone who wants a more guided starting point, although a user who values traditional card functionality may find the secured-card route more useful over time.
Credit-monitoring apps solve a different problem. They can help users watch scores, reports, or account changes, but monitoring alone does not create a repayment habit. I see Ava as more action-oriented than a tool that only displays credit information. On the other hand, it should not be treated as a full credit-monitoring replacement if the user wants a broad view of every account and report detail.
A bank account or budgeting app is also complementary rather than interchangeable. A budget tells me whether I can afford an obligation; Ava focuses on the credit-building activity itself. I would use a budget or spreadsheet to plan the money first, then use the finance app as one part of the credit routine. Replacing that planning step with the app would be a mistake.
The trade-offs that deserve attention
The biggest trade-off is focus versus flexibility. A narrow product can be easier to understand, but it may not satisfy users who want rewards, extensive account controls, investment tools, bill management, or a complete financial dashboard. I would not download Ava expecting it to organize every part of my financial life.
There is also a behavioral trade-off. The app’s credit-building purpose may encourage healthier attention to repayment, but it still involves credit. If I am already struggling to cover essentials, taking on a new obligation can add pressure rather than improve my situation. In that case, a free budgeting tool, debt counseling, or a conversation with a qualified financial professional would be a better first step.
Another point of friction is that credit outcomes are not instant. A user may complete the right actions and still need patience before seeing meaningful changes in their broader credit profile. I would avoid judging the app after only a brief period or assuming that one product controls every factor affecting a score. Credit history, existing accounts, payment behavior, and other circumstances all matter.
Privacy and account security should be considered carefully with any finance app. I would use a strong device passcode, avoid sharing login details, and review every permission or financial connection before approving it. These are not reasons to reject Ava specifically; they are sensible safeguards whenever an app is involved in personal financial information.
Small workflows that make the experience safer
My preferred workflow would begin with a “repayment first” rule. Before using any available credit, I would move or reserve the money needed to cover it. That turns the activity into a planned transaction instead of a gamble on next month’s income. If I cannot reserve the money, I would not use the credit facility for that purchase.
I would also set a weekly review rather than checking only when a payment is due. During that review, I would compare the app’s activity with my own bank balance and budget. This catches problems earlier, especially when several small transactions are easier to overlook than one large purchase.
A third useful tactic is to keep credit-building separate from emergency borrowing. If the car needs an unexpected repair or an essential bill is due before payday, I would not automatically use Ava simply because it is available. A product designed to build credit should not become a reflexive solution for every cash-flow problem.
Finally, I would periodically compare the app with alternatives instead of assuming I must stay with it forever. As my credit history develops, a secured card, a conventional card, or a different financial service may become a better fit. Starting with a focused app does not mean giving up the right to change tools when my needs change.
Who benefits most from Ava Finance
I think Ava is best suited to a beginner who wants a credit-building path with a clear purpose and who can already afford the related repayments. It may also help someone rebuilding their financial routine after avoiding credit, provided they approach it cautiously and keep essential expenses separate from credit activity.
The app is less suitable for a person looking for a broad banking replacement, a rewards-focused card, detailed investment management, or a comprehensive credit-report service. It is also a poor match for anyone who expects guaranteed or immediate score improvement, or who plans to use credit to cover regular shortfalls.
The age rating of Everyone makes the app broadly accessible from a content perspective, but accessibility should not be confused with financial readiness. I would still want a user to understand borrowing, repayment, and personal budgeting before relying on any credit product. A young or inexperienced user may benefit from discussing the arrangement with a trusted adult or financial professional.
Version, availability, and my final recommendation
The current version is 5.1.6626, and the app supports operating systems from version 9 onward. That makes it practical for many Android users with older compatible devices, though I would still keep the operating system and app updated for security and reliability. Since it is free to install, the main decision is not the download cost; it is whether the credit-building approach fits my financial behavior.
After looking at the app through that lens, I would recommend it to a friend who wants a focused starting point and can commit to checking obligations, reserving repayment money, and avoiding unnecessary borrowing. I would explain that the app can support a habit, but it cannot replace a budget or guarantee a particular credit result.
My honest view is that Ava works best as a controlled training ground for credit responsibility, not as extra spending power. If that distinction is clear, the app’s focused design can be useful. If I wanted maximum flexibility, rewards, or a complete financial command center, I would choose a more traditional alternative. For the right beginner, though, Ava Finance offers a straightforward way to make credit-building an intentional part of a broader money plan.
FAQ
What is Ava Finance, and what can I use it for?
Ava Finance is a personal finance application designed to help users organize, monitor, and better understand their money. Depending on the version and region, it may offer tools for tracking spending, reviewing balances, managing budgets, and viewing financial activity in one place. Before downloading, check the official app listing to confirm the currently supported features and whether the service is available in your country.
Is Ava Finance safe to use with my financial information?
Because a finance app may handle sensitive information, security should be one of the first things you evaluate. Ava Finance may request access to account or personal details to provide its features, so review its privacy policy, permissions, encryption information, and authentication options before connecting anything. Use a strong password, enable available security protections, and download only from an official app store or verified source.
Does Ava Finance connect directly to bank accounts or financial services?
The available connection options can vary according to your location, financial institution, and the current version of Ava Finance. Some users may be able to link supported accounts, while others may need to enter information manually or use limited tracking tools. Read the in-app explanations carefully before authorizing access, and verify which institutions are supported so you know exactly what information the application can retrieve.
Is Ava Finance free, or does it include subscriptions and extra charges?
Ava Finance may provide free features while reserving certain tools, advanced functions, or services for a paid plan. Pricing, trial periods, and subscription conditions can change, and they may differ between Android and iOS. Check the app-store description and the payment screen before starting a trial. Pay particular attention to automatic renewal, cancellation deadlines, and whether any transaction or service fees apply.
What should I check before downloading Ava Finance?
Before installing Ava Finance, confirm that your device meets the required Android or iOS version and that the app is available in your region. Review recent user feedback, the developer information, requested permissions, privacy policy, and update history. You should also consider whether the app supports your currency, banks, and financial goals. Never share banking credentials outside the application’s official secure sign-in process.


